The 2026 Section 179 deduction limit is $2,560,000 (for tax years beginning in 2026). Section 179 lets businesses deduct the full purchase price of qualifying equipment and software in the year it's placed in service, rather than depreciating it over several years. This guide covers the full 2026 rules - dollar limits and phase-outs, vehicle caps, qualifying property, and how Section 179 combines with bonus depreciation.
What Is Section 179 (and Why Does It Matter in 2026)?
Section 179 of the Internal Revenue Code empowers businesses to deduct the full purchase price of qualifying equipment and software in the same tax year they're put into service. Instead of stretching depreciation across several years, you can claim the entire cost upfront - dramatically improving your cash flow and creating immediate tax benefits.
Why Section 179 Matters for Your Business
- Immediate Tax Impact: Rather than waiting years for depreciation benefits, claim the deduction in 2026
- Enhanced Cash Flow: Keep more working capital in your business when you need it most
- Strategic Growth: Upgrade equipment sooner and maintain competitive advantages in your market
Quick Reference: 2026 Section 179 Limits
Max Deduction (2026):
$2,560,000
(phase-out begins above $4,090,000)
Bonus Depreciation:
100%
(applies after Section 179)
New & Used Equipment:
Qualifies for full Section 179 deduction
Specialized (Non-Passenger) Vehicles:
Qualifies for full Section 179 deduction
Certain SUVs (6,000-14,000 lbs GVWR):
$32,000 max first-year Section 179; remainder depreciated
Business-Use Requirement:
>50% business use; deduction limited to % of business use
Example: How Does Section 179 Generate Tax Savings?
This simplified example illustrates how Section 179 can reduce after-tax equipment costs. It assumes the purchase qualifies and the business has enough taxable income to use the full Section 179 election. For a $125,000 purchase:
- Section 179 Deduction: $125,000 (the full purchase price - well under the 2026 limit)
- Total Tax Savings: $43,750 (assumes a 35% combined tax rate)
- Final Equipment Cost: $81,250
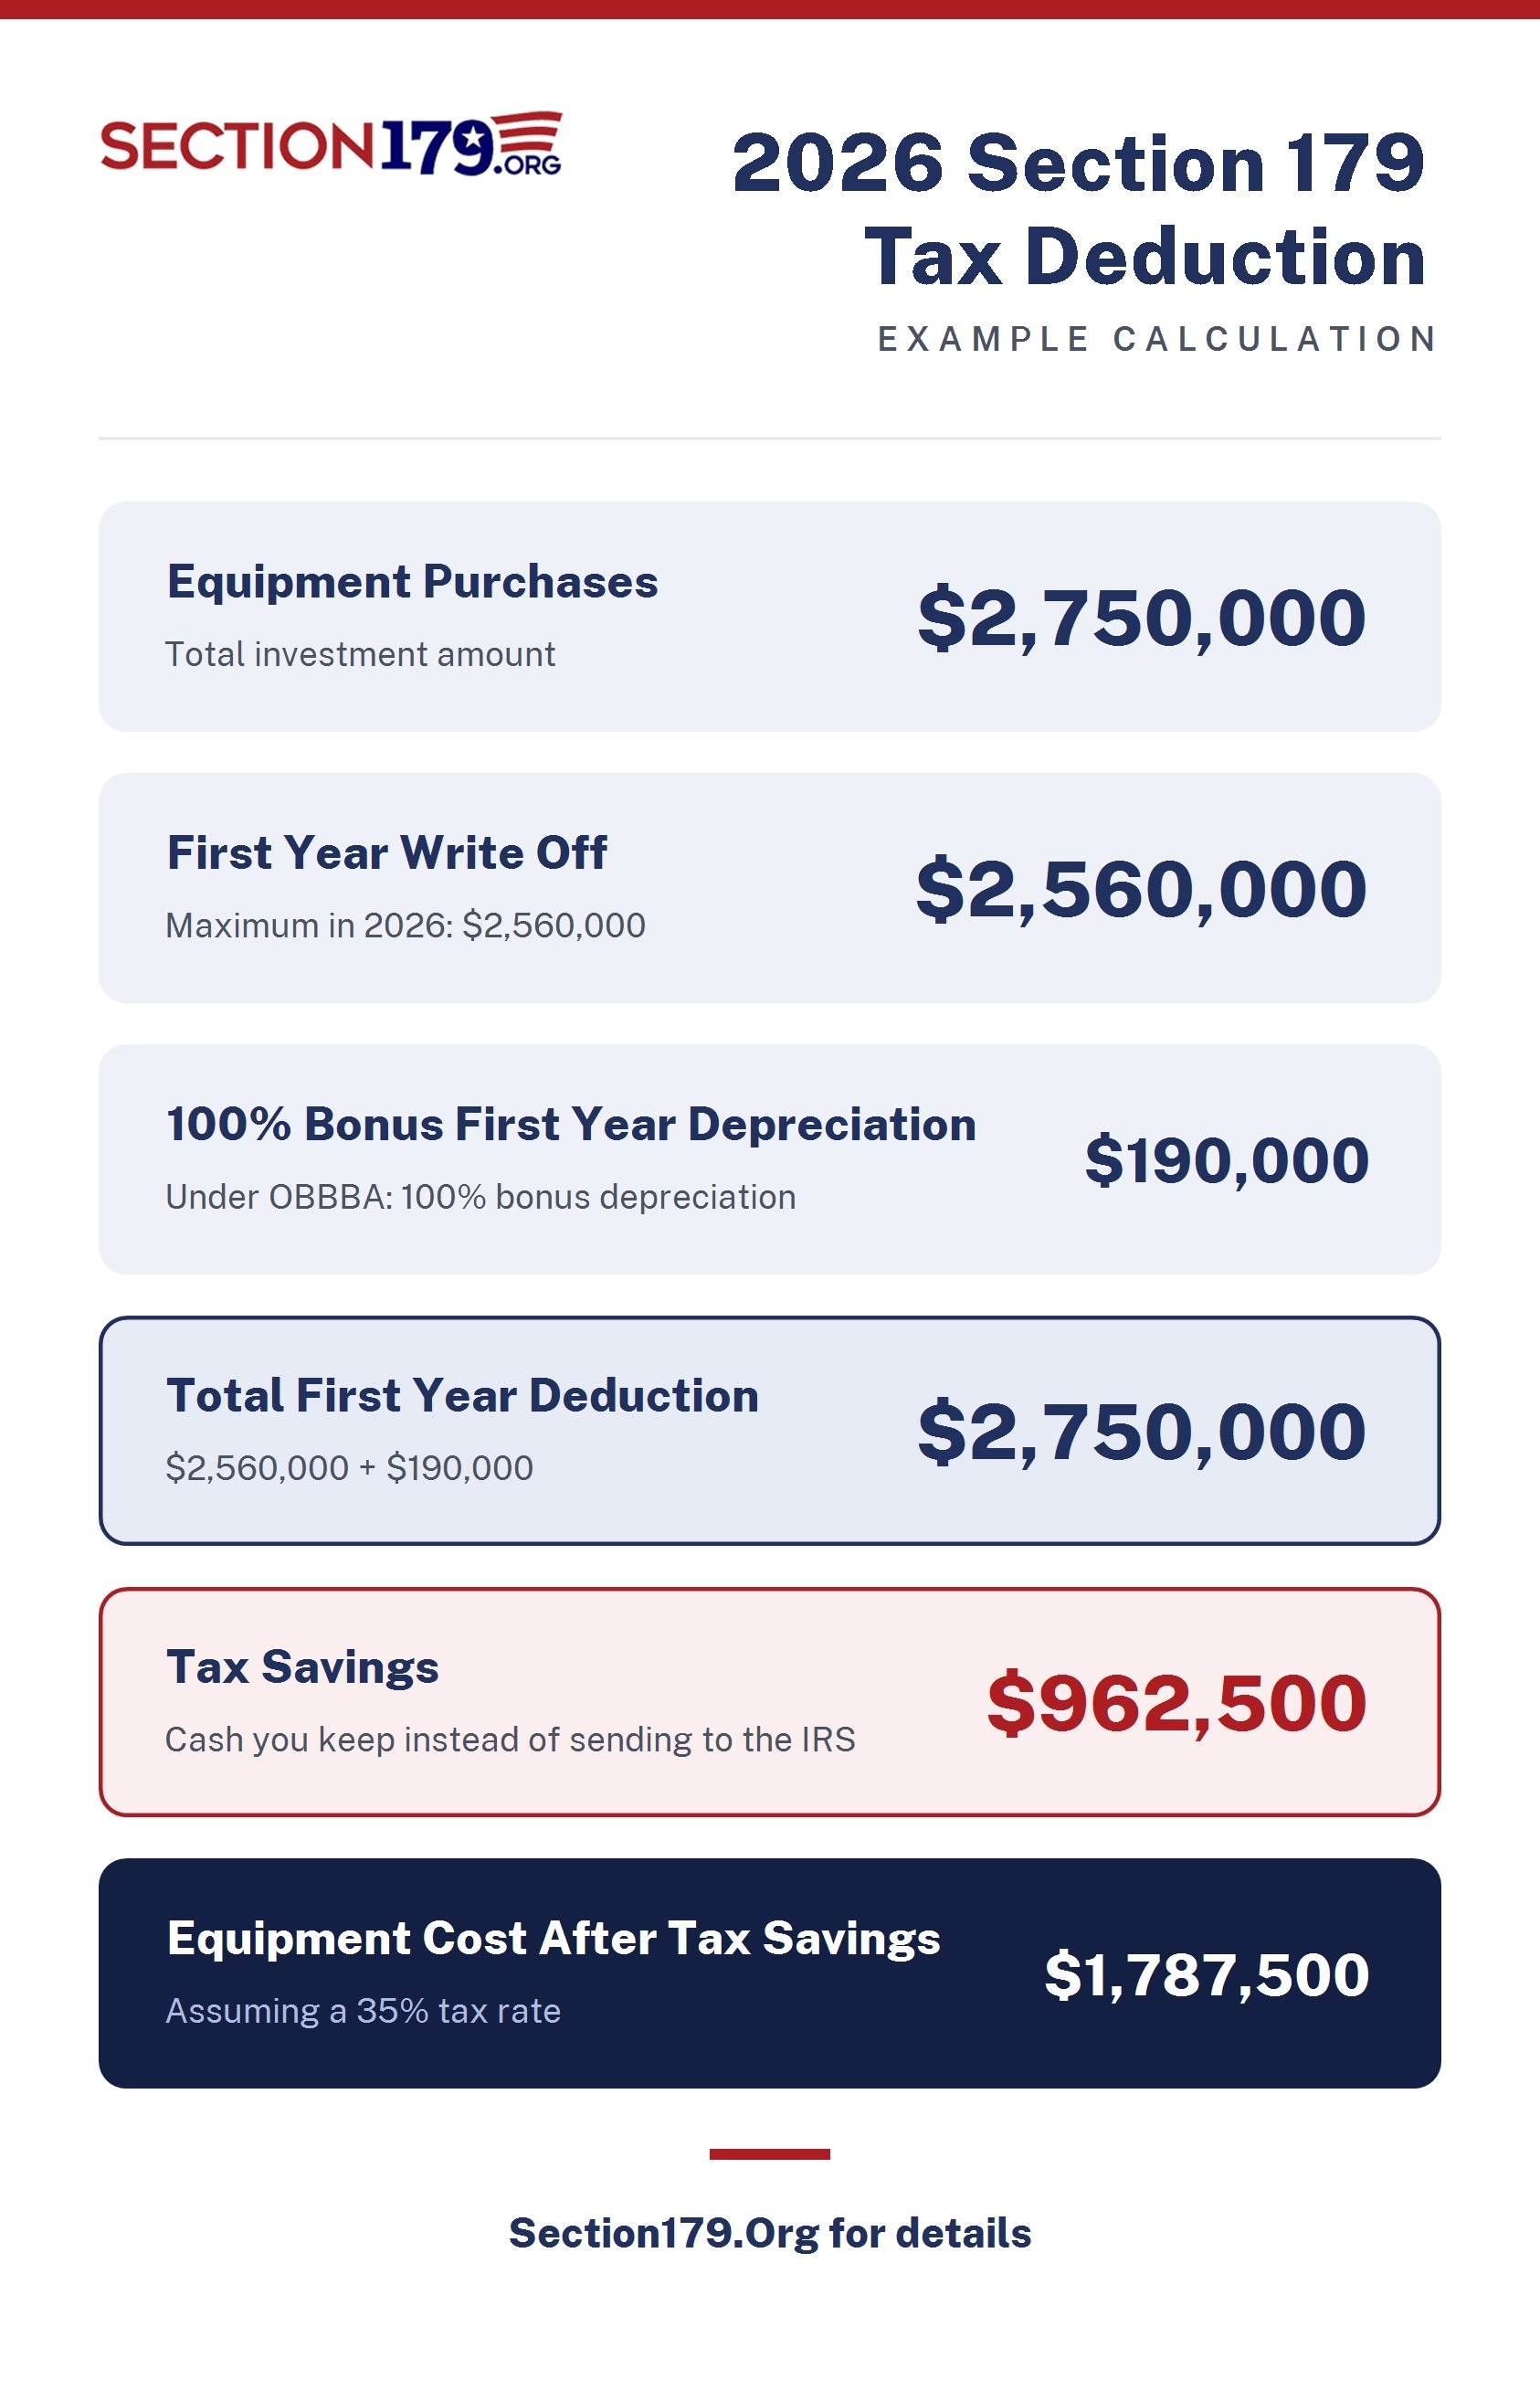
For larger purchases that exceed the deduction limit, bonus depreciation can cover the remaining eligible basis. Our annual Section 179 example infographic shows a worked example at full scale - free to download and share (a link back to Section179.Org is appreciated):
How the 2026 Deduction Limits and Phase-Out Threshold Work
What Is the Maximum Section 179 Deduction for 2026?
For tax years beginning in 2026, businesses can elect to expense up to $2,560,000 of qualifying purchases. This is the maximum total Section 179 amount you can write off, subject to the taxable income limitation and the phase-out rules below.
- Placed in service during the tax year you're claiming the deduction
- Used for business purposes more than 50% of the time
- Qualifies under IRS guidelines
Spending Cap and Phase-Out Rules
The Section 179 deduction begins to phase out when the total cost of qualifying property placed in service exceeds $4,090,000:
- Phase-out begins: above $4,090,000 of total qualifying property placed in service
- Dollar-for-dollar reduction: the $2,560,000 limit is reduced by the amount over $4,090,000
- Fully phased out: at $6,650,000
- After Section 179: remaining basis may still qualify for bonus depreciation (if eligible)
How Does Section 179 Apply to Business Vehicles?
Special rules apply to vehicles:
- Vehicles rated at 6,000 lbs. GVWR or less follow standard depreciation rules
- SUVs over 6,000 lbs. GVWR but under 14,000 lbs. GVWR: Limited to $32,000 Section 179 deduction for certain SUVs
- Vehicles over 6,000 lbs. GVWR such as heavy work trucks and vans may be eligible for full Section 179 expensing
- Vehicles with beds at least six feet long are not subject to the SUV limitation
How Do Carryover & Limitations Work?
Your Section 179 deduction cannot exceed your business's net taxable income. However, if your Section 179 election exceeds your taxable business income in a given year, you can choose a partial Section 179 election. Any unused portion of the deduction carries forward to subsequent tax years, allowing you to apply it once you have sufficient income. This means if you can't fully utilize Section 179 in the current year, you retain the remaining deduction for future use - ensuring you never lose the benefit.
What Are the Requirements for Qualifying Property?
- Must be primarily for business use (>50%)
- New or used equipment qualifies
- Must be placed in service by the end of your tax year (December 31, 2026 for calendar-year taxpayers)
- Must be acquired by purchase from an unrelated party - inherited or gifted property doesn't qualify, and neither do purchases from related parties (for example, your spouse, parent, or child, or a business you own or control)
How Does Section 179 Compare to Bonus Depreciation in 2026?
- Section 179: $2,560,000 maximum (tax years beginning in 2026) with a taxable income limitation and phase-out rules
- Bonus Depreciation: generally 100% for qualified property acquired and placed in service after Jan. 19, 2025
- Common approach: use Section 179 first, then apply bonus depreciation to any remaining eligible basis
What Are Expert Tips for Maximizing Section 179 in 2026?
- Plan Major Purchases Around Tax Years: Time your acquisitions to maximize immediate write-offs.
- Track Business Usage Carefully: Logging usage is crucial for vehicles and other assets.
- Consider State Tax Implications: Different states may have unique limits or rules.
- Maintain Detailed Records: Keep documentation for five+ years in case of audit.
- Review Annually with a Tax Professional: Tax laws can shift year to year; stay current.
Please see https://www.section179.org/section_179_deduction/ for more information.
How can we help?
* Indicates a required field